
Do NFC Payments Need the Internet?
How Tap-to-Pay Really Works
Contactless payments have become part of everyday life. At shops, restaurants and ticket machines, a quick tap of a card, smartphone or smartwatch can complete a purchase in seconds.
But do NFC payments need an internet connection?
The short answer is that NFC itself does not need the internet. It allows compatible devices to exchange information when they are placed close together. However, the wider payment process may still require connectivity to verify and authorize the transaction.
What Is NFC?
NFC stands for Near Field Communication. It allows compatible devices to exchange small amounts of information over a distance of only a few centimetres.
NFC is commonly used in:
Contactless credit and debit cards
Mobile payment wallets
Smartwatches
Public transport cards
Access badges and hotel keys
Product tags
Unlike Wi-Fi or mobile data, NFC is designed specifically for close-range communication. The card or device must be brought near an NFC reader before information can be exchanged.
Does NFC Need an Internet Connection?
No. When you tap a card or phone, its NFC chip communicates directly with the payment terminal using short-ran:
Can a card or phone communicate with the terminal without internet? Yes.
Can the entire payment be completed without connectivity?
Sometimes, but not always.ge radio signals. This exchange does not require Wi-Fi or mobile data on the customer’s device.
However, NFC is only the beginning of the payment process. The terminal may still need to connect to:
The merchant’s payment processor
The card network
The customer’s bank
Fraud-detection services These systems decide whether the transaction should be approved. Therefore, it is helpful to separate two questions:
What Happens When You Tap a Contactless Card?
A contactless bank card contains a chip and an NFC antenna. When the card is held near a compatible terminal, the two exchange the information needed to begin the transaction.
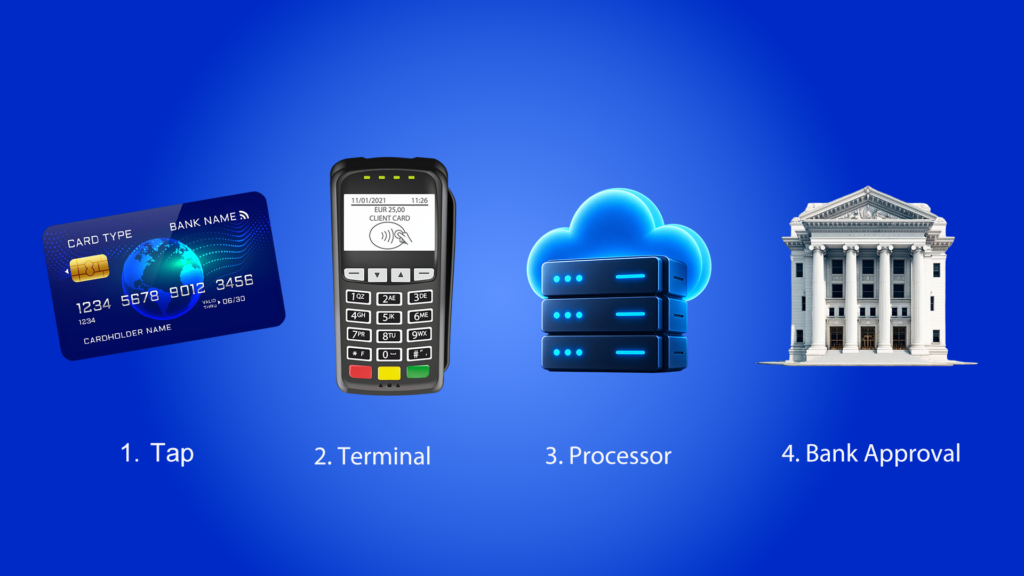
A typical contactless payment works like this:
The customer taps the card.
The card and terminal communicate through NFC.
The terminal sends the transaction to the payment processor.
The card issuer approves or declines it.
The result is returned to the terminal.
The NFC exchange happens only at the beginning. Most of the authorization process takes place through the payment infrastructure behind the terminal.
What About Smartphones and Smartwatches?
Mobile wallets also use NFC, but they may handle payment information differently from physical cards.
Many mobile wallets use tokenization. Instead of giving the merchant the original card number, the wallet uses a substitute payment credential linked to the device or service.
The user may also need to approve the payment with:
A fingerprint
Facial recognition
A device passcode
Another authentication method
A phone does not necessarily need an active mobile-data connection for the NFC exchange. However, whether the payment can proceed depends on the wallet, device, card issuer and terminal.
Can Contactless Payments Work Offline?
Some contactless transactions can be accepted without immediate online authorization. These are often called offline payments.
An offline transaction does not necessarily remain offline permanently. The terminal may apply predefined risk rules, store the transaction temporarily and submit it when connectivity returns.
Whether an offline payment is possible can depend on:
The transaction amount
The card or wallet
The merchant’s payment setup
Bank and payment-network rules
Local regulations
Security limits built into the system
Offline payments are receiving renewed attention as providers look for ways to improve reliability in areas with unstable connectivity.
In September 2026, for example, India introduced an NFC tap-to-pay option for its UPI network designed to work in areas with limited or no network coverage.
That does not mean every NFC card, mobile wallet or payment terminal can work offline. The relevant payment system must specifically support the feature.
Contactless Cards and Mobile Wallets Are Different
Although both can use NFC, physical cards and mobile wallets are not identical.
A contactless card contains a chip issued by a bank or card provider. A mobile wallet stores a digital payment credential on a phone or wearable device. It may also use tokenization and device authentication to protect the transaction.
The important distinction is that NFC describes how nearby devices communicate. It does not define how payment information is stored or how the transaction is authorized.
What Information Can NFC Read?
NFC is not limited to payments. Compatible apps can use it to read information made available by supported tags and cards.
The available information depends on the object and its security rules. A product tag may contain a website address, while a transport card, access badge and bank card each follow different standards.
With a supported contactless bank card a compatible reader may be able to access certain information made available by the chip. However, this does not turn the reader into a payment terminal or provide access to the owner’s bank account.
Sensitive information such as a PIN or CVV is not normally provided through NFC. Reading available card information and making a payment are separate functions.
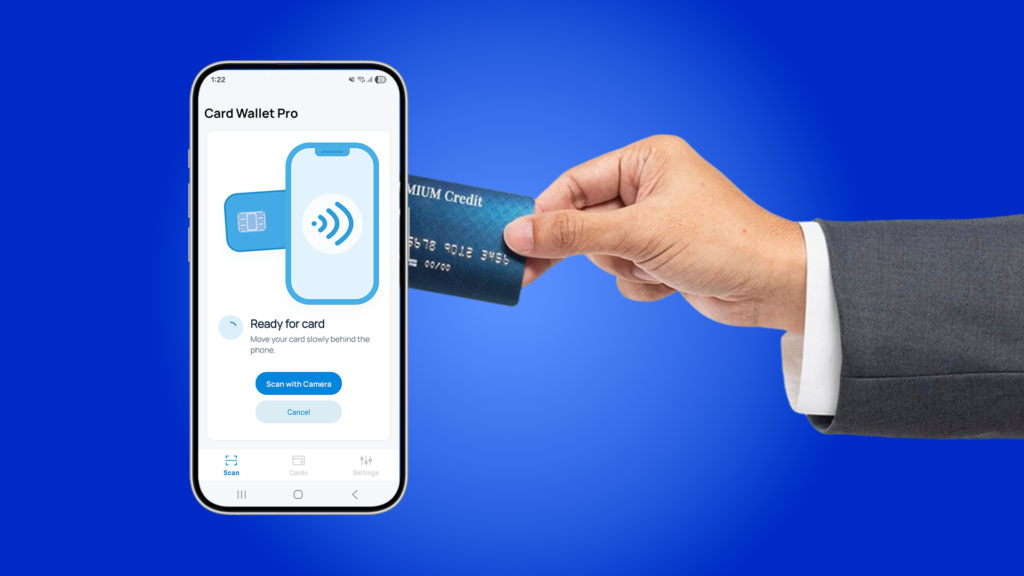
This distinction is important for NFC card-reading and card-organization applications. They may help users read or organize supported information from their own cards, but they do not automatically enable tap-to-pay transactions.
Are NFC Payments Secure?
Contactless payment systems use several measures to help protect transactions, including:
Very short communication distance
Chip-based transaction security
Payment tokenization
Device authentication
Transaction limits
Fraud monitoring
PIN or additional verification requests
Users should still take sensible precautions:
Protect cards and devices physically
Use a strong device passcode
Enable biometric protection
Review transaction notifications and statements
Report lost cards or devices quickly
Install apps only from trusted sources
Never share PINs or security codes
NFC is a communication technology, not a security guarantee. The card, wallet, terminal and payment infrastructure all play a role in protecting information.
Common NFC Myths
“NFC and Wi-Fi are the same.”
They are different technologies. NFC works over a very short distance, while Wi-Fi connects devices to a network over a much greater range.
“Your phone always needs mobile data to tap.”
Not necessarily. The phone can communicate with the terminal through NFC without mobile data, although another part of the payment system may still need connectivity.
“Every NFC app can make payments.”
No. An app may read NFC tags or supported card information without being able to initiate payments.
“NFC reveals everything on a card.”
No. The information available depends on the card’s design and security rules. A PIN or CVV is not simply broadcast when the card is tapped.
The Future of Tap-to-Pay
NFC is likely to remain important because it makes everyday interactions quick and familiar. People already use the same tapping gesture to pay, board public transport, open doors and exchange digital information.
Future developments may include:
Better offline payment support
More phones used as merchant payment terminals
Additional payment-enabled wearables
Digital identity integrations
Stronger connections between payments and loyalty programs
The change is not simply about replacing physical cards. Phones, watches and digital wallets are becoming gateways to several services at once.
So, Do NFC Payments Need the Internet?
NFC itself does not need the internet. A card, phone or wearable can communicate directly with a nearby terminal using short-range radio technology.
The wider payment process, however, often requires connectivity somewhere in the system. Some payment methods support limited offline transactions, while others require immediate online authorization.
The simplest explanation is:
The tap can happen without the internet, but completing the payment may still require connectivity.
At MaxSoft, our interest in NFC extends beyond payments. We explore how mobile devices can read, organize and make useful information easier to access while keeping the purpose and limitations of each technology clear.
More Like This:
Keep Your Payment Cards Organized and Within Reach
Managing several credit, debit, business or backup cards can quickly become...
A Simple, Secure, Privacy-First Way to Manage Your Cards
Most of us use more than one card today. Personal cards, business cards, backup...


Get Started
Let’s Achieve Something Extraordinary
At MaxSoft, we turn ideas into intelligent solutions, from AI innovation to app development and design. Partner with us to create technology that makes an impact.

Building intelligent digital products that empower businesses and people. From AI solutions and mobile apps to web design and software development, we transform ideas into innovation.